

 October 16, 2026
Categories: Headline / Business/Finance / Money Matters
Rapid Fire Financial Shaylas


Q: What are the best long-term inflation hedges?
A: There are inflation hedges that protect your investments and inflation hedges that protect your lifestyle. A strong career is one of the most effective lifestyle hedges because your income should rise over time along with the cost of living. Skill development, job stability, and career flexibility all help your human capital keep pace with inflation. A thirty‑year fixed mortgage is another powerful tool. Even though rates are high today, locking in a payment that never changes, while your income and assets grow, can turn into a long‑term inflation advantage. You continue to build financial strength while the mortgage stays flat.
When it comes to investments, the biggest mistake is assuming an inflation hedge is something that reliably increases whenever inflation rises. No asset behaves that way consistently. Inflation comes in different forms, and different assets respond to different types of inflation. A diversified portfolio that blends productive assets, inflation‑linked bonds, and sensible liquidity is usually more dependable than making a large bet on one idea. Staying disciplined and avoiding reactionary decisions often matters more than finding the perfect hedge.
Stocks have historically helped over long periods because companies can raise prices, which can increase revenue and earnings. They can still struggle during sharp inflation spikes, especially when interest rates rise quickly. TIPS are the most direct hedge against United States inflation. Their principal adjusts with the CPI, and interest payments adjust as well. They work best for money you expect to spend during a specific future period. They still carry duration risk, so long maturities can move in ways you may not like. If that feels too complicated, it is reasonable to avoid them.
Real estate can help through rising rents and property values. It is a tangible asset, sensitive to interest rates, but comes with meaningful costs. Taxes also matter because inflation interacts with tax rules in ways that can erode real returns, especially for fixed income.
There is no single perfect hedge. The goal is to build a mix of assets and lifestyle choices that keep your financial life resilient across many different inflation environments.
Q: How do you find the best mutual funds and ETFs?
A: There is no such thing as the best. Every major asset manager offers essentially the same building blocks. The names change, the fees vary, and the structures differ, but the underlying exposures are similar. The goal is not to find the best; that can only be known with hindsight. The goal is to find reasonable investments that fit your portfolio and help you reach your objectives.
Many amateur investors choose funds in their 401(k) by simply picking whatever had the highest long‑term returns. They often use the same approach in their regular accounts. The problem is that past performance does not guarantee future results. The strongest returns are usually concentrated in one part of the market, and markets move in cycles. What looked great over one stretch can be shvach in the next.
Good portfolio construction starts with understanding the core building. Large‑cap United States stocks, international stocks, and investment‑grade bonds are core. Venture capital, a tech fund, and DreckCoin are not. Allocate most of your capital, roughly ninety‑five percent, to eight to twelve core asset classes. If you want to speculate on non-core with the remaining five percent, that is fine.
Next, decide how you want exposure to those core areas. You can use mutual funds, ETFs, SMAs, or certain partnership structures. What makes the most sense may depend on preferences, personal circumstances, investor psychology, or account type. Operational simplicity matters more than people realize. A portfolio with fewer moving parts is easier to monitor, easier to rebalance, and easier to stick with. Behavioral fit matters too. Some investors handle the day‑to‑day movement of ETFs better than mutual funds, and others prefer the structure of an SMA because it feels more deliberate. The right choice is often the one you can stay committed to without second‑guessing yourself every week.
Then evaluate fees. Understand where you can get proper exposure at a modest cost and where paying more might be justified. When you follow this approach, you build a sensible portfolio that supports your goals instead of chasing past performance and taking unnecessary risk.
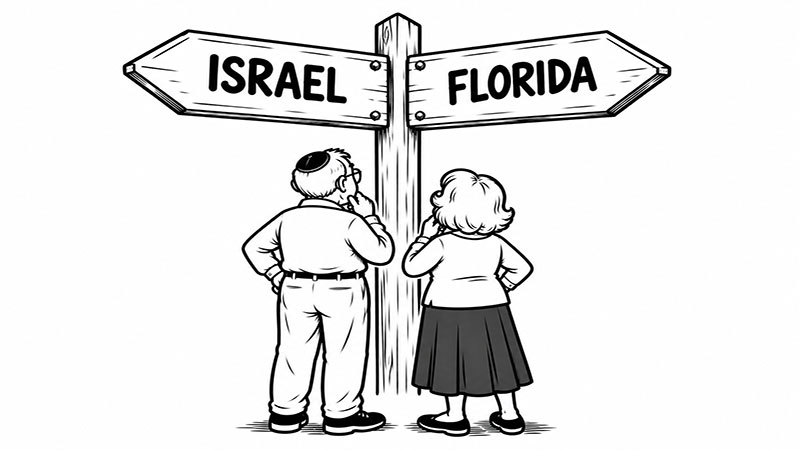
Q: My wife wants to retire to Florida and I want to retire to Israel. How do we handle this disagreement?
A: It is amazing how much financial planning is not about math and instead depends on communication, family dynamics, and perspective. The key is to stop treating this as Florida versus Israel and start treating it as a conversation about how each of you wants your retirement to look.
Begin by understanding the reasons behind each preference. Your wife may care most about family, weather, cost, healthcare, lifestyle, or familiarity. You may be focused on community, Jewish life, religious connection, culture, or the desire to spend your later years in Israel. Once you identify the underlying goals, you may find the disagreement is smaller than it seems.
Family involvement can also matter. If children or grandchildren are part of the picture, their location, needs, and proximity may influence how each of you feels about where to live. Sometimes the real issue is not geography but how connected you both want to remain to the people who matter most.
Then compare the two options realistically. Look at housing, taxes, healthcare, travel, family proximity, social networks, climate, activities, and the day‑to‑day experience of living in each place. Do not rely on idealized versions of Florida or Israel. Picture an ordinary Tuesday.
You can also test each option before committing. Spend several months in Florida and several months in Israel. Another possibility is splitting the year, especially if both places offer something meaningful to each of you.
Most importantly, neither spouse should treat this as a negotiation with a winner and a loser. Retirement is a major transition, and both people need to feel excited about the life they are building. The goal is not to prove which location is objectively better. It is to find an arrangement you can both look forward to.
And if none of this works, let the grandchildren vote. They will be honest, and you will listen. That is how most Jewish family decisions get made anyway.